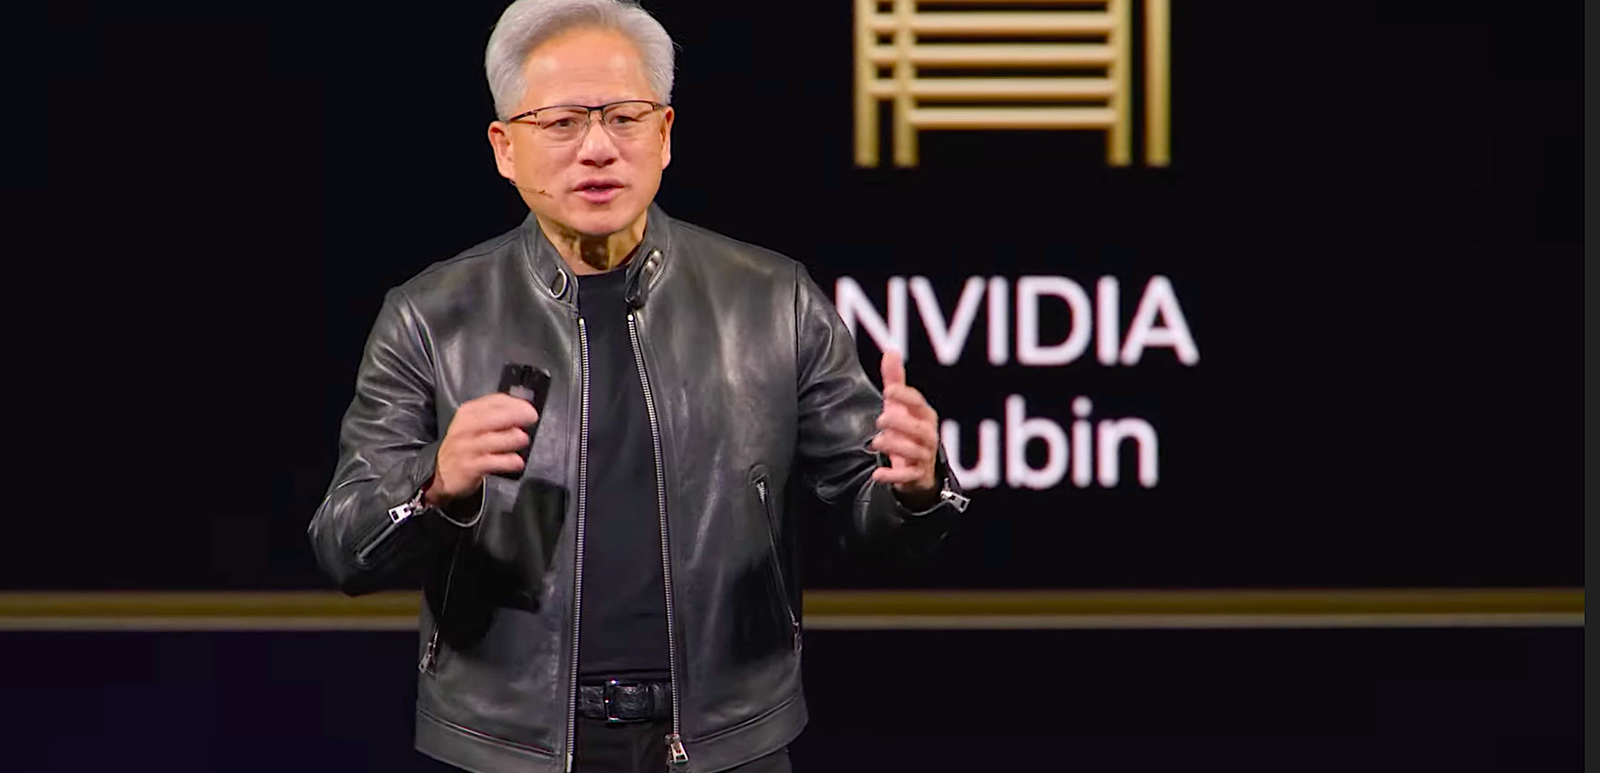
Nvidia Corp. has once again rewritten the playbook for Silicon Valley financial performance, delivering a quarterly earnings report that outstripped even the most bullish Wall Street projections. Propelled by an astronomical surge in enterprise demand for accelerated computing hardware, the semiconductor giant reaffirmed its undisputed supremacy at the core of the global artificial intelligence boom. For market analysts, tech executives, and macroeconomic observers, the numbers offer much more than a routine corporate victory lap; they provide a comprehensive barometer for where enterprise infrastructure budgets are flowing and how deeply artificial intelligence is embedding itself across the global economy.
The first crucial takeaway is the relentless momentum of Nvidia's data center segment, which surged by more than ninety percent year-over-year. Management characterized customer appetite for its latest architecture as parabolic, emphasizing that cloud hyperscalers, national governments, and private enterprises are continuing to treat computational infrastructure as an existential investment. The transition from legacy general-purpose central processing units to accelerated computing clusters is no longer a speculative pilot program. Instead, enterprise procurement teams are viewing advanced graphics processing units as foundational utility assets comparable to modern power grids or high-speed telecommunications backbones.
A second major development lies in the rapid operational ramp-up of the next-generation Blackwell computing platform. Addressing earlier market anxieties regarding packaging bottlenecks and liquid-cooling thermal complexities, Nvidia confirmed that production yields are scaling aggressively to meet an unprecedented backlog. Chief executive Jensen Huang emphasized that Blackwell represents not merely a faster chip, but an integrated full-stack computing system that combines specialized networking fabrics, custom silicon switches, and advanced software libraries to dramatically slash the cost of large-scale model inference.
Third, the report highlighted a notable diversification in Nvidia's revenue sources, with sovereign artificial intelligence emerging as a multi-billion-dollar catalyst. Nation-states across Europe, the Middle East, and Asia are allocating substantial public funds to establish domestic high-performance computing centers to train foundation models on localized cultural and linguistic datasets. This trend insulates Nvidia against potential capex lulls from commercial hyperscalers, anchoring hardware demand in national sovereignty, cybersecurity, and regulatory compliance imperatives.
Fourth, Nvidia demonstrated that the ongoing shift from training generative models to live real-time inference is expanding margins rather than eroding them. While skeptics long warned that inference workloads could shift toward commodity application-specific integrated circuits, Nvidia’s proprietary software ecosystem, particularly CUDA and Triton Inference Server, continues to exert massive developer gravity. Enterprises value architectural consistency and rapid deployment flexibility over custom silicon that requires prolonged optimization cycles.
Finally, the broader implication for the technology sector is that the anticipated return on investment reckoning has been deferred once again. Venture capital sentiment, corporate earnings guidance, and tech valuations remain tightly tethered to Nvidia’s sustained forward trajectory. Rather than cooling off, the hardware foundation of the intelligence era is accelerating, signaling that computing power will remain the primary currency of global digital transformation for years to come.